DSCR loan in Tampa Bay financing solves a major hurdle for real estate investors in Tampa, Sarasota, and Bradenton whose personal income does not fit conventional lending guidelines.That is exactly the gap a DSCR loan is built to close.
DSCR Loan, Defined
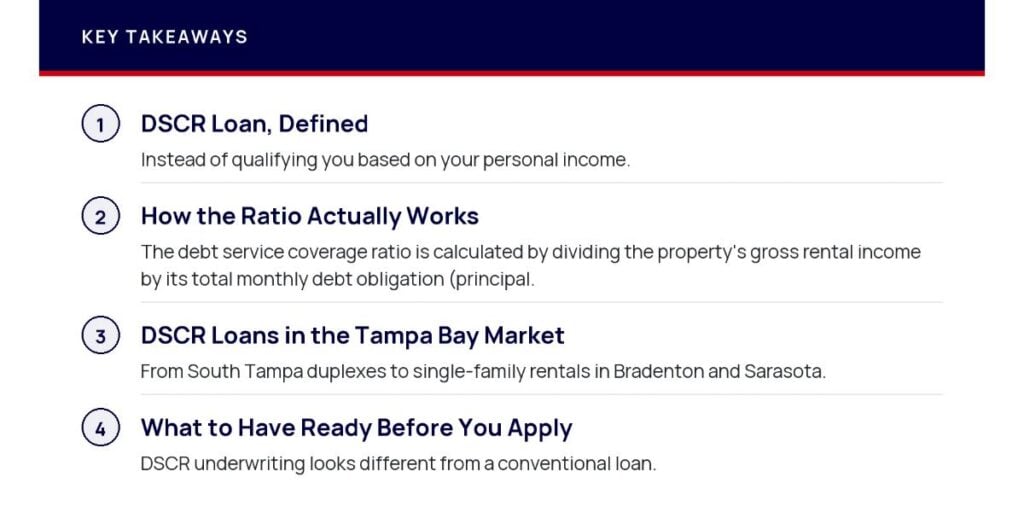
DSCR stands for debt service coverage ratio. Instead of qualifying you based on your personal income, tax returns, and employment history the way a conventional loan does, a DSCR loan qualifies the property based on the rental income it generates compared to its mortgage payment. If the numbers on the property work, the loan can work, regardless of what your W-2 or Schedule C looks like.
How the Ratio Actually Works
The debt service coverage ratio is calculated by dividing the property’s gross rental income by its total monthly debt obligation (principal, interest, taxes, insurance, and any HOA dues). A ratio of 1.0 means the rent exactly covers the mortgage payment. Most lenders like to see a ratio above 1.0, though some programs allow for slightly lower ratios depending on the rest of the deal.
Who a DSCR Loan Is Built For
- Self-employed investors whose tax returns understate their real cash flow
- Buyers who already have multiple mortgages and are running into conventional lending limits
- Out-of-state or international investors targeting the Tampa Bay rental market
- Anyone buying a short-term or long-term rental property where the numbers stand on their own
Using a DSCR Loan in Tampa Bay Real Estate
From South Tampa duplexes to single-family rentals in Bradenton and Sarasota, Tampa Bay’s rental demand has stayed strong, which is part of why DSCR financing has become such a common tool here. Because there is no personal income verification in the traditional sense, closings can also move faster than a conventional investment property loan, which matters in a market where good deals do not sit long.
What to Have Ready Before You Apply
DSCR underwriting looks different from a conventional loan, but you should still expect to provide a lease or market rent estimate, an appraisal that includes a rent schedule, proof of funds for the down payment and reserves, and basic entity documentation if you are purchasing through an LLC. A larger down payment, often in the 20 to 25% range, is typical for DSCR financing.
Frequently Asked Questions
How does a DSCR loan work for rental property investors in Florida?
The lender looks at the rental income the property can generate relative to its mortgage payment, rather than qualifying you based on personal income or tax returns. If the rent-to-payment ratio meets the program’s minimum, the loan can move forward.
Do I need a good credit score for a DSCR loan?
Credit still matters for pricing and approval, but the qualification process is centered on the property’s cash flow rather than a full personal income review.
Can I use a DSCR loan for a short-term rental in Tampa Bay?
Many DSCR programs allow short-term rental income to be considered, though documentation requirements vary. It is worth reviewing your specific property and market with a lender familiar with short-term rental underwriting.
Talk to a Tampa Bay Lender Who Understands Investor Financing
Golf Phuphanich and the team at Lendworkz LLC work with investors across Tampa, Sarasota, Bradenton, St. Petersburg, Clearwater, Wesley Chapel, Lutz, Lakewood Ranch, and South Tampa on DSCR, conventional, jumbo, and FHA financing. If you have an investment property in mind and want to evaluate a DSCR loan in Tampa Bay, call (813) 299-3320 or visit lendworkz.com.
Golf Phuphanich, NMLS #291838. Lendworkz LLC, NMLS #2780991. Company: Lendworkz LLC, 18711 N Dale Mabry Hwy, Lutz, FL 33548 NMLS Consumer Access reference on file: www.nmlsconsumeraccess.org
